 Kerbio
What goes into it
Deposit, stamp duty with the surcharge, buying costs, any refurbishment, and the product fee if you don't add it to the loan.
Rent after empty weeks, less letting, maintenance, insurance and service charges, less the mortgage payment.
Rent must cover the interest by 125% or 145% at a stressed rate. It caps how much you can borrow.
Weighing up your own name against a company in more detail? Use the rental income tax calculator. For the rent to expect, the LHA rates by postcode give a floor in every area of England.
Questions
How much deposit do I need for a buy-to-let?
Usually 25% of the price, sometimes 20% or 40% depending on the lender and the rent. On top of the deposit you pay stamp duty (with the 5% surcharge on an additional property), legal and survey fees, and often a lender's product fee.
What is the buy-to-let rental stress test?
Lenders check the rent covers the mortgage interest with room to spare, at a higher test rate than you'll actually pay. A common test is rent of 125% of the interest at 5.5% for basic-rate taxpayers and limited companies, and 145% for higher-rate taxpayers. Five-year fixes are often tested at the actual rate. Every lender sets its own, so treat the result as a guide.
Is buy-to-let still worth it?
It depends on the numbers for the specific property. Put in the real rent, costs and mortgage rate: if the cash flow after tax and the return on the cash you put in beat what else you could do with that money, it may be. Growth in value is extra, but not guaranteed.
Interest-only or repayment?
Most buy-to-let mortgages are interest-only, which keeps the monthly payment lower and cash flow higher; you repay the loan when you sell or remortgage. A repayment mortgage costs more each month but pays the loan down. For tax, only the interest counts; capital repayments never do.
How is tax worked out here?
Using the same engine as our rental income tax calculator: your own name after Section 24, or a limited company after corporation tax and dividend tax, at 2026/27 or 2027/28 rates. England, Wales and Northern Ireland. It is an estimate, not tax advice.
Your maximum offer, and every option side by side
The Kerbio Buy-to-Let Calculator works out the most you can pay to hit your target cash flow and still pass the lender's rent test. Then try a lower rate, more refurb or a different rent in up to four options next to your deal, and see which wins. Tax in your own name or a company included.
See the spreadsheet, £19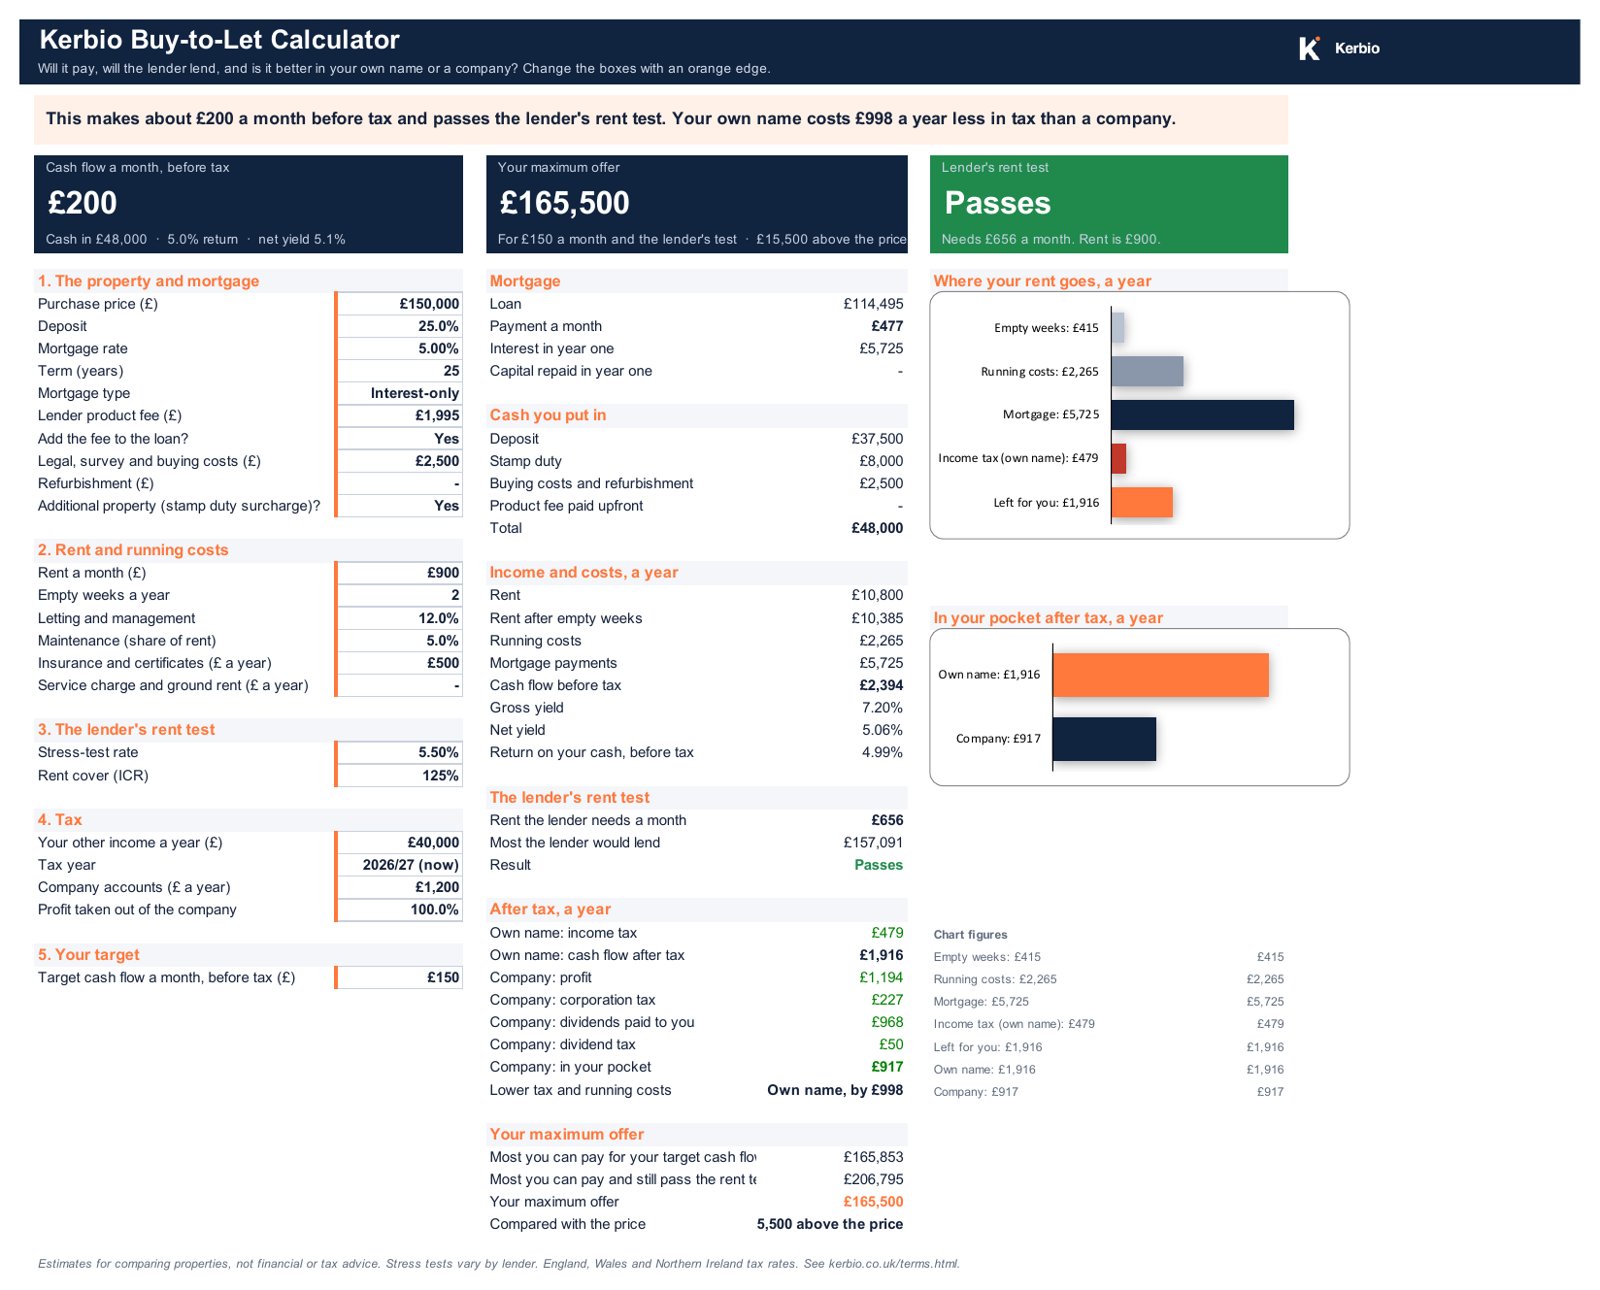
Other free calculators
About these calculators
Free, with no sign-up, made by Kerbio, a small independent UK tool for property investors. Nothing you type leaves your browser. Figures are indicative and this is general information, not financial or tax advice.
We also make a Chrome extension that shows sold prices, LHA, licensing and Article 4 on every Rightmove, Zoopla and OnTheMarket listing.
See the extension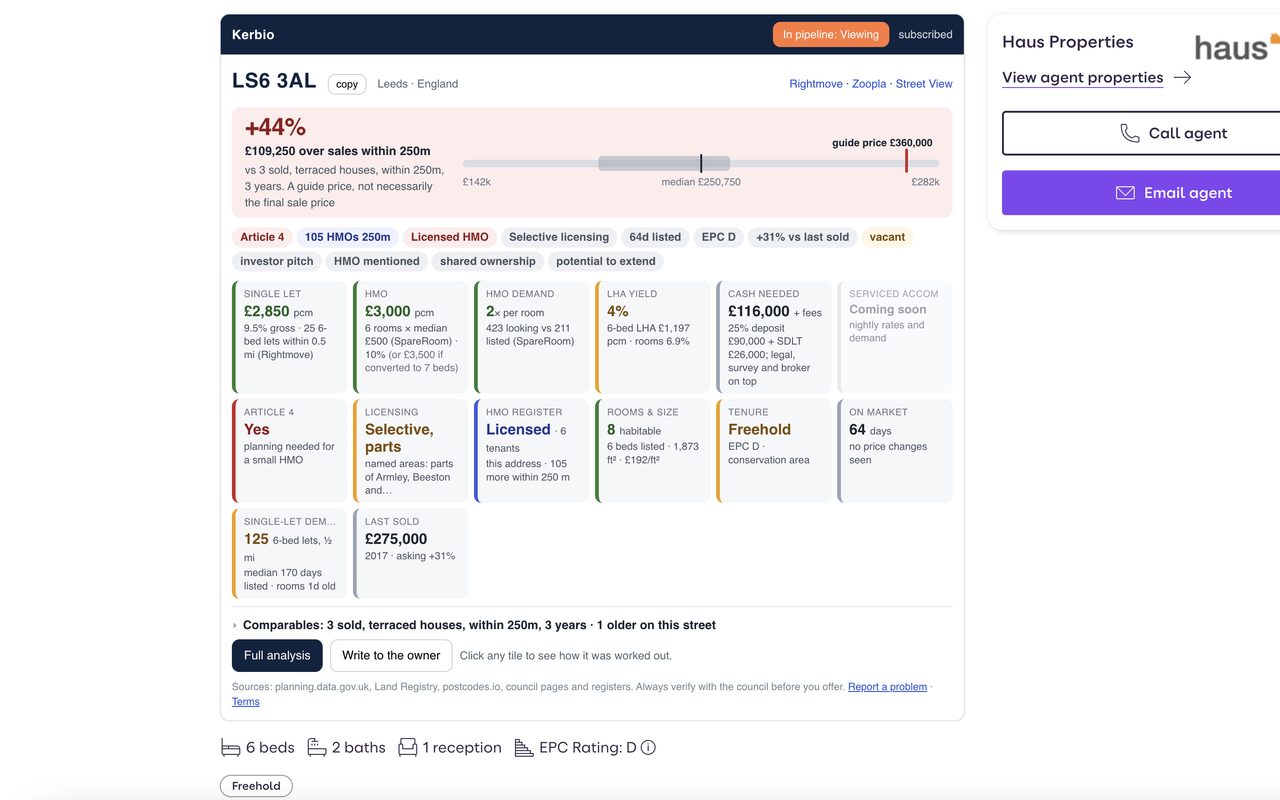
Stamp duty: GOV.UK residential rates with the 5% additional property surcharge. Tax: GOV.UK income tax, dividend and corporation tax rates for 2026/27, and the property income changes from April 2027. Stress tests vary by lender. Estimates only, not financial or tax advice.