 Kerbio
Watch: the Buy-to-Let Calculator, step by step (1 min 40)
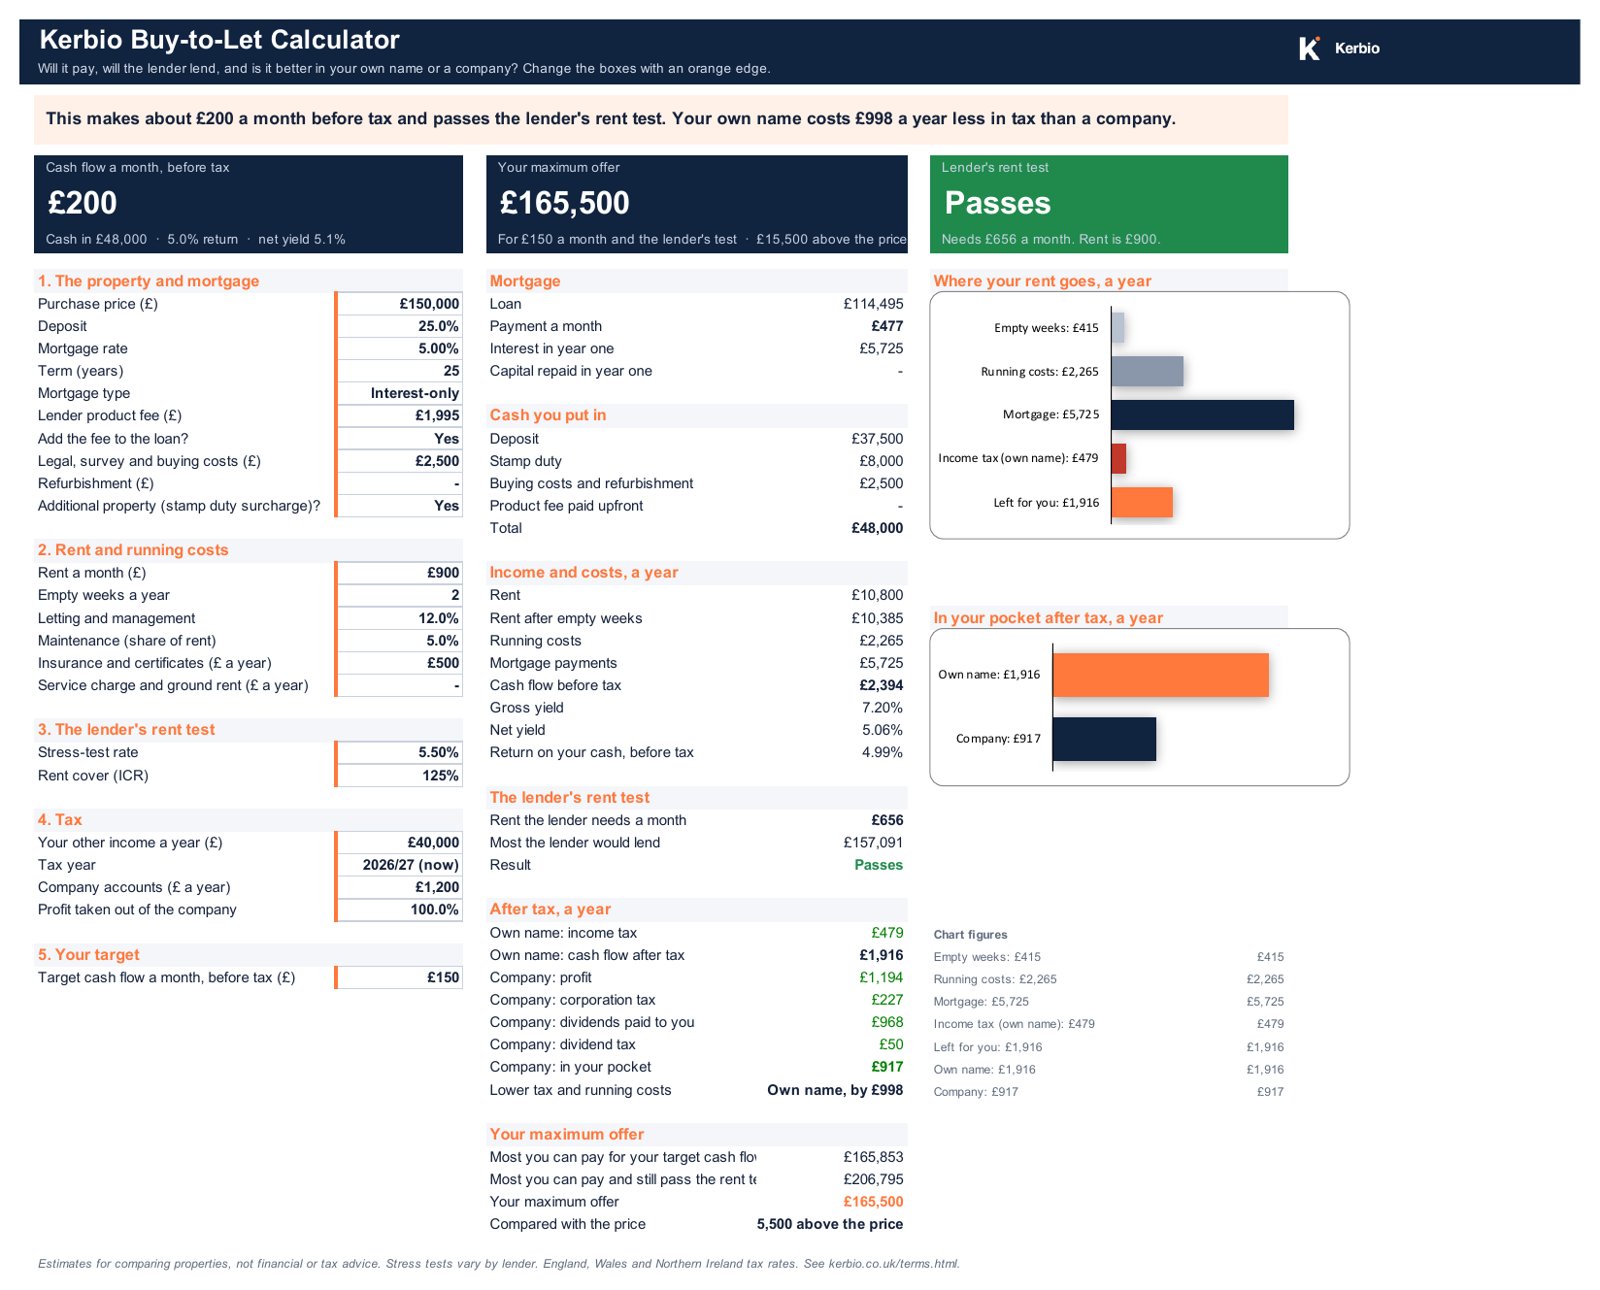
What it tells you
The most you can pay to make your target cash flow each month and still pass the lender's rent test.
Your deal plus four options: change the rate, refurb, rent or price, or add a different house. What you change lights up and the best result turns green.
Monthly and yearly, after empty weeks, letting fees, maintenance, insurance and the mortgage.
Whether the rent passes at 125% or 145%, the rent needed, and the most a lender would lend.
Income tax after Section 24, against corporation tax and dividend tax, and which leaves you more.
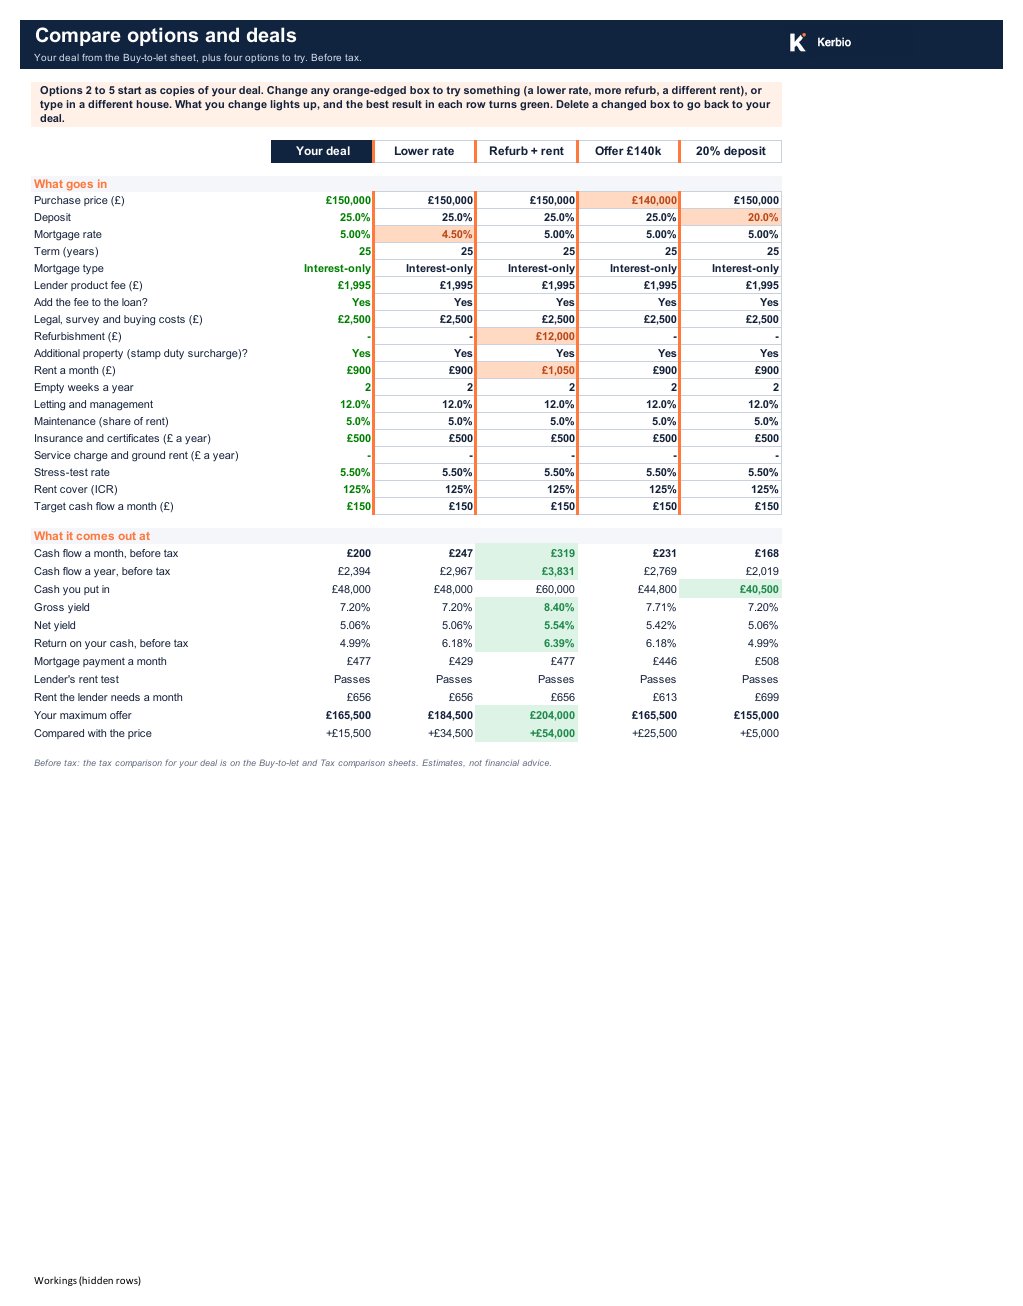
Try every option side by side
Same £150,000 house, four ways to play it. A lower rate, a refurb with higher rent, a lower offer and a smaller deposit, next to your deal. Change any box and it lights up; the best result in each row turns green.
- Lower rate: maximum offer up from £165,500 to £184,500.
- Refurb and £1,050 rent: best cash flow, £319 a month.
- 20% deposit: least cash in, £40,500, but the maximum offer drops to £155,000.
Same house, two landlords, different answers
A £150,000 house let at £900 a month, 25% deposit, 5% interest-only. Before tax it makes about £200 a month and passes a 125% rent test (the lender needs £656).
- Landlord earning £40,000: own name is better, by £998 a year.
- Landlord earning £65,000: a company is better, by £509 a year.
Same property, opposite answers. That's why the question is so confusing, and why it's worth running your own numbers.
What's inside
- Start here: how to use it and what the results mean
- Buy-to-let: a plain-English verdict, your maximum offer, result tiles and two live charts, with every figure behind them
- Compare: your deal plus four options side by side, with the best result in each row highlighted
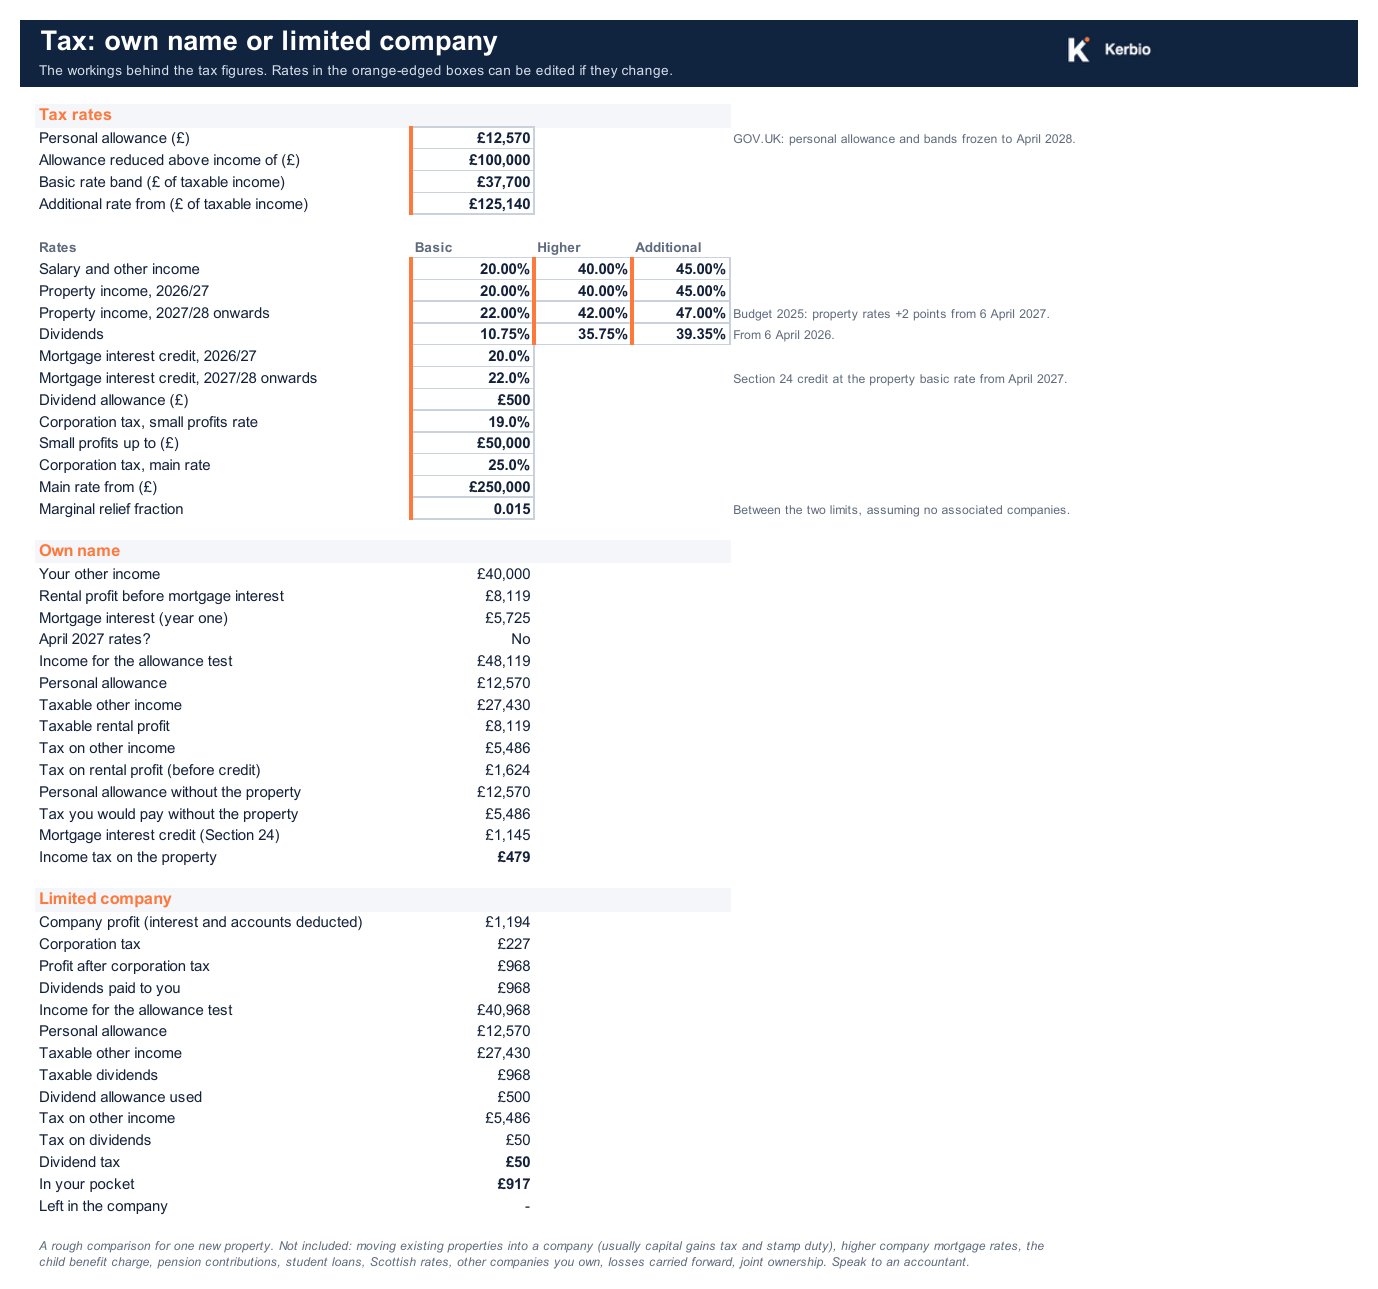
- Tax comparison: the workings, step by step, with editable rates
- Stamp duty: editable bands with the additional property surcharge
- Landlords buying a first or next buy-to-let
- Anyone deciding between their own name and a company for a new purchase
- Checking a deal will pass the lender's rent test before you offer
- Bridging, BRRR and maximum offers: that's the Deal Analyser
- Moving properties you already own into a company
- Replacing an accountant or broker
Questions
How is the maximum offer worked out?
You set the cash flow you want each month. The spreadsheet works out the most you can pay so that rent, less empty weeks, running costs and the mortgage, still leaves that much, and the most you can pay while still passing the lender's rent test. Your maximum offer is the lower of the two, rounded down to the nearest £500.
How do the options work?
On the Compare sheet, options 2 to 5 start as copies of your deal. Change any box, such as the rate, refurb, rent or price, or type in a different house. The boxes you change light up, and the best result in each row turns green.
What do I need to use it?
Microsoft Excel on Windows or Mac. It is built and tested in Excel; it uses standard formulas, so it should also open in Google Sheets and Apple Numbers.
How does it compare own name and limited company?
It works out income tax on the rental profit in your own name after Section 24, then the same property through a company: corporation tax, then dividend tax on the profit you take out. Every step is shown on the Tax comparison sheet.
Does it include the April 2027 changes?
Yes. Choose 'From April 2027' and property income is taxed at 22%, 42% and 47%, with the mortgage interest credit at 22%. The rates are editable if they change again.
Does it tell me whether to use a company?
It shows the numbers for the property you put in. It doesn't include the cost of moving properties you already own into a company, which is usually capital gains tax and stamp duty. Speak to an accountant before deciding.
How was it tested?
Against hand-worked examples, including the personal allowance taper above £100,000, and against our free web calculator's engine on 300 random deals, with every output matching.
Is this financial or tax advice?
No. It is a calculator for comparing properties. Stress tests vary by lender and tax depends on your whole situation.
Kerbio Buy-to-Let Calculator, version 1.2
One Excel file, yours to keep. Instant download.
For buyers in the UK. Outside the UK? Email us before buying.
Made by Kerbio, a small independent UK tool for property investors. Want the free versions first? Try the buy-to-let calculator and the rental income tax calculator. Estimates, not financial or tax advice.